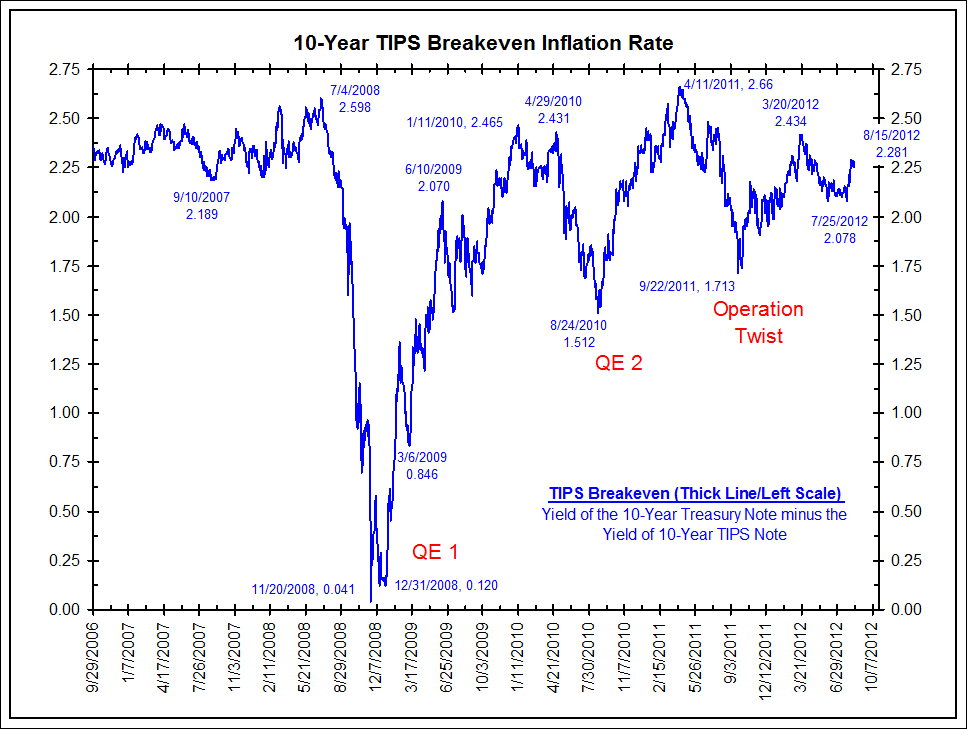
1) What’s The Holdup With QE3? by James Bianco @ The Big PictureAs the chart below shows, the Federal Reserve has never initiated more accommodation when the TIPS inflation breakeven rate was above 2.0%. This level is important because the Federal Reserve adopted 2.0% as an inflation target last January.
When expected inflation is above 2.0%, it does not mean the FOMC has to tighten. But it can mean there is too much inflation to add more accommodation. Of course the Federal Reserve can decide to ignore this target, but since they adopted it less than a year ago, they risk their own credibility in doing so.
This might be the big stumbling block to QE3.
Click to enlarge:
Source: Bianco Research
Woj’s Thoughts - Maybe this time will be different, but recent economic data has been generally supportive of moderate growth and US stocks are approaching post-recession highs. I stand by my previous statement: “With a Presidential election approaching, the Fed will likely err on the side of caution to avoid the perception of taking sides. Therefore, if the Fed doesn’t act in June, absent a collapse, it may not act at all in 2012.”
2) Nicholas Kaldor On The Common Market by Ramanan @ The Case for Concerted Action"… Some day the nations of Europe may be ready to merge their national identities and create a new European Union – the United States of Europe. If and when they do, a European Government will take over all the functions which the Federal government now provides in the U.S., or in Canada or Australia. This will involve the creation of a “full economic and monetary union”. But it is a dangerous error to believe that monetary and economic union can precede a political union or that it will act (in the words of the Werner report) “as a leaven for the evolvement of a political union which in the long run it will in any case be unable to do without”. For if the creation of a monetary union and Community control over national budgets generates pressures which lead to a breakdown of the whole system it will prevent the development of a political union, not promote it."
[italics in original]
That was written in 1971! In The Dynamic Effects Of The Common Market first published in the New Statesman, 12 March 1971 and also reprinted (as Chapter 12, pp 187-220) in Further Essays On Applied Economics - volume 6 of the Collected Economic Essays series of Nicholas Kaldor.
Woj’s Thoughts - Talk about being prescient! This “dangerous error” is playing out in real-time as Europe attempts to push through a full economic union in hopes that it will lead to political union. I remain highly skeptical of this course of action, which I believe is making a political union increasingly improbable (and I was already a Euro-pessimist). An eventual break-up of the EMU remains the most likely outcome, in my opinion, although it may still be a few years away. If hopes of a future political and economic union are to persist, it will be necessary for the EU to maintain free trade and labor mobility.
3) Enron, Lehman Brothers, and… Netflix? by microfundy @ MicrofundyEither way (enough of these SEC filings), what this means is that NFLX really has ANOTHER $869.53M of “current” (due within one year) liabilities that wasn’t included on their balance sheet.
They also have ANOTHER $2.97B (B, as in Billion!) of long term liabilities.
…
Although NFLX Book Value stays constant because a corresponding line gets added into their asset part of the balance sheet, THOSE ASSETS don’t produce any ADDITIONAL cash flows/earnings. THEY ARE ALREADY ASSUMED IN NFLX MODELS!
Also, all of the metrics that an investor would look at when analyzing the health of the balance sheet, involve debt. Whether looking at debt/equity, debt/assets, debt coverage ratios etc. Those are all tremendously understated!
Woj’s Thoughts - Anyone who thinks that corporate accounting is becoming more comprehensive or clean should carefully read through the notes sections of various SEC filings. Netflix is a highly visible, US company, that managed to obscure nearly $5 billion in liabilities from its balance sheet. Odds are that Netflix is not alone in this respect.
Under Keynes’s tutelage, Britain’s currency, Sterling, was in 1933 revived as a money managed by the Bank of England and protected from speculative and vested private financial interests. Then in 1934, President Roosevelt freed the dollar, and with it, the people of the United States, who then embarked on a period of sustained recovery. Sadly, Germany maintained the dictates of Gold Standard economic policies throughout the 1930s – and we all know the political consequences of that incompetence.
If Europe were now to abandon the Gold Standard-type policies that underpin the Euro, Europeans would feel the full force of private wealth’s anger, through allies in the media, academia and politics. But this will follow from fear – not reason.
So, European leaders, be as bold as Keynes and Roosevelt. You have nothing to lose but the ‘gold fetters’ that deny the people of Europe economic and democratic sovereignty, and that chain you to the interests of private wealth.
There is however, everything to gain from European convergence, prosperity, unity and peace.”
Read it at Debtonation
An open letter to the leaders of Europe: Abandon the Euro's 'gold fetters'
By Ann Pettifor
Many people are finally coming around to the notion that a common Euro currency is effectively the same as a gold standard. By removing each country's sovereignty over their currency, the Euro vastly limits the options by which countries can enact counter-cyclical fiscal or monetary policies. The gold standard proved, on numerous occasions, that in times of crisis countries will ultimately abandon the commitment. This crisis will prove no different as countries will defect from the common currency. These actions, however, should not devalue the gains from convergence in trade and labor mobility. Protecting the European Union, while abandoning the common currency, should be the top priority.
Related posts:
Chidem Kurdas - "free trade and markets matter much more than the euro"
Ending the Euro Currency, Not the European Union
Creating the euro was a different level of ambition from building a common European market. The latter had historical roots. There had been free flow of goods, capital and people across parts of Europe in the 19th century and earlier. Political barriers and wars disrupted those flows, but at times and in places free trade and free migration across national borders was a reality. Indeed, by mid-20th century older people remembered with nostalgia how easy travel had once been.
Hence by removing the barriers to the movement of goods, money and people, the European Union was not imposing a novel blueprint. Had it stopped with free markets, tremendous economic and political benefits would have been achieved with little downside. I have to admit that I never understood the aggressive drive to impose a common currency.
Read it at ThinkMarkets
Euro Crisis from Long Perspective
By Chidem Kurdas
Many people appear to still hold hope that the current EU crisis will ultimately resolve itself in the creation of a United States of Europe. Kurdas contrasts the historical conditions of the US and Europe prior to accepting a common currency. His conclusion, similar to that of Peter Boone and Simon Johnson in The End Of The Euro: A Survivor’s Guide, is worth repeating:
what needs to be kept in mind is that free trade and markets matter much more than the euro. Preserving them should be the priority.
Related posts:
Ending the Euro Currency, Not the European Union
For the last three years Europe’s politicians have promised to “do whatever it takes” to save the euro. It is now clear that this promise is beyond their capacity to keep – because it requires steps that are unacceptable to their electorates. No one knows for sure how long they can delay the complete collapse of the euro, perhaps months or even several more years, but we are moving steadily to an ugly end.
Whenever nations fail in a crisis, the blame game starts. Some in Europe and the IMF’s leadership are already covering their tracks, implying that corruption and those “Greeks not paying taxes” caused it all to fail. This is wrong: the euro system is generating miserable unemployment and deep recessions in Ireland, Italy, Greece, Portugal and Spain also. Despite Troika-sponsored adjustment programs, conditions continue to worsen in the periphery. We cannot blame corrupt Greek politicians for all that.
It is time for European and IMF officials, with support from the US and others, to work on how to dismantle the euro area. While no dissolution will be truly orderly, there are means to reduce the chaos. Many technical, legal, and financial market issues could be worked out in advance. We need plans to deal with: the introduction of new currencies, multiple sovereign defaults, recapitalization of banks and insurance groups, and divvying up the assets and liabilities of the euro system. Some nations will soon need foreign reserves to backstop their new currencies. Most importantly, Europe needs to salvage its great achievements, including free trade and labor mobility across the continent, while extricating itself from this colossal error of a single currency.
Read it at The Baseline Scenario
The End Of The Euro: A Survivor’s Guide
By Peter Boone and Simon Johnson
The last sentence requires special attention. Much of the discussion today regarding a dissolution of the EMU seems to imply that free trade and labor mobility must rapidly decline. As frustrations between and within nations are allowed to grow, this outcome may prove true but it need not. The benefits from free trade and labor mobility in the EU are significant regardless of whether any single currency exists. If that were not the case, then why are some countries part of the EU but not the EMU?
In politics it often appears that planning for unthinkable outcomes is considered a sign of expected failure. Confidence, however, cannot solve all problems. Unthinkable outcomes still happen frequently enough and the repercussions are far greater than necessary. Even if the politicians will not make their contingency plans publicly known, one has to hope those plans are being thoroughly discussed in the background. An end to the Euro currency will be troublesome, but an end to the EU will be disastrous.

