Showing posts with label US Treasuries. Show all posts

Wednesday, February 20, 2013

(Late) 2013 Predictions

Last year I took a chance and threw my own projections into the ring. Similar to Byron Wien and Edward Harrison, I mostly selected events that were widely seen as having a low probability (less than 33%) but which I believed held a greater than 50% chance of occurring. The final results were a bit disappointing, but that won’t stop me from trying again this year. Since these predictions already represent a late release, without further adieu, here are the 2013 predictions:

1) Spain requests access to ECB’s OMT - Since ECB President Mario Draghi announced the OMT program, yields on Spanish debt have fallen rather dramatically. Although this eases financing pressure, it has done little to alter the actual economy’s downward spiral. During 2012 Spain’s GDP growth became increasingly negative, falling by 1.8% year-on-year in the fourth quarter. Meanwhile unemployment continues its meteoric rise to over 26% for the general population and nearly 60% for youth. With the large banks still severely undercapitalized and households over-indebted, private sector lending continues to decline:
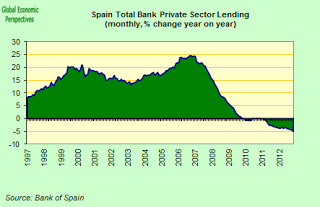


Seeing no recovery and potentially a worsening decline, “bond vigilantes” will eventually test Draghi’s threat. At that point Spain will be forced to accept a Memorandum of Understanding (MoU) in return for ECB bond-buying through the OMT program.

2) The Euro finishes the year above $1.30 - After falling nearly 10% during the first half of 2012, the euro has more than recouped its losses on the back of optimism and deflationary policies.
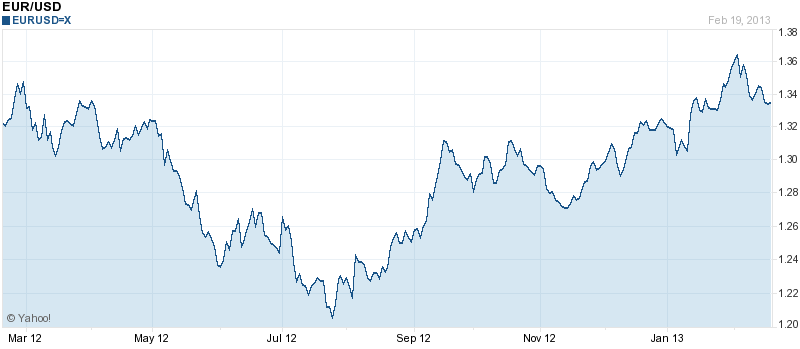
At points during 2013 the optimism is likely to fade, but I expect politicians and central bankers will take the necessary steps to quell fears for the time being. Unfortunately those steps will involve further deflationary policies that push the euro higher. These competing forces will largely cancel out, leaving the euro close to or above where it began the year.

3) The Eurozone remains in recession the entire year - Forecasters now expect euro-zone economic activity to be flat this year, down from a previous prediction of 0.3% growth made just three months ago. Last year saw practically continuous downgrades to GDP growth forecasts and I expect this year to be no different. Austerity measures are momentarily easing, but more will likely be enacted based on the outcomes of several elections. The recent appreciation of the euro against several major currencies will also dampen growth by putting pressure on net exports. With banks across Europe trying to build up capital and persistently high unemployment, the private sector will remain especially weak. Though Germany may experience a temporary rebound, the Eurozone as a whole will not register GDP growth this year.

4) The Japanese yen rises above 90 per $ - Since the election of PM Shinzo Abe, the yen has fallen fast and is down more than 20% from recent highs.
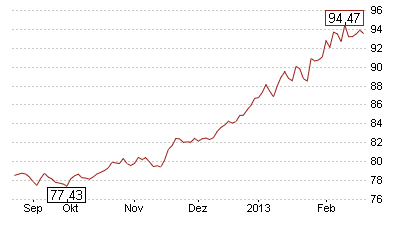
During this time the Nikkei has risen more than 20%, yet yields on Japanese sovereign debt are little changed. This suggests many foreigners may be speculating on the supposedly forthcoming monetary and fiscal stimulus. As previously stated, the fiscal stimulus will probably be small and short-term. On the monetary front, short of actually entering the foreign exchange market, the Bank of Japan (BOJ) has essentially no mechanism to spur inflation and thereby cause a sustained depreciation of the yen. When market participants recognize the inability of Japan to avoid continued deflation, the yen will return to appreciating against the dollar.

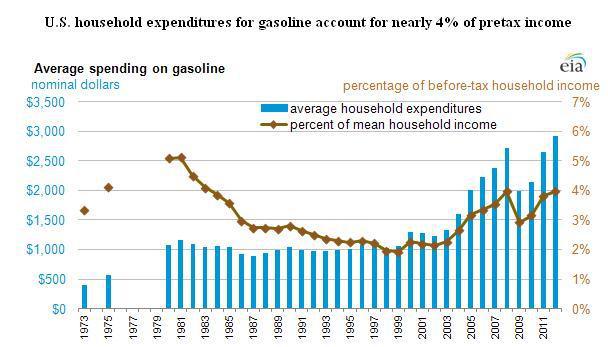
5) Gas prices will peak above $4.20 per gallon and set a new yearly record-high average above $3.75 per gallon - Gasoline prices have been on the rise for the past 31 days, currently averaging approximately $3.75 per gallon. Though this current streak will probably end soon, prices are unlikely to give back much of the gains before beginning the typical rise into summer. The ongoing potential for flare ups in the Middle East will keep prices elevated throughout the year. Higher gas prices, which already account for 4% of before-tax household income (chart below), will be a drag on consumer spending in 2013.

6) U.S. Yearly GDP growth falls below 1.5% - Forecasts of ~3% annual GDP growth over the past couple years have been overly optimistic as real growth in 2011 and 2012 was merely 1.6% and 1.9%, respectively. Apparently forecasters are being a bit tamer in their estimates this year, now expecting only 2% annual growth. Unfortunately I suspect these estimates will once again prove too optimistic. Various tax hikes and the upcoming sequester (which will go through in some respect) will reduce the budget deficit by a few percent this year. Housing is likely to remain a bright spot, but further declines in interest rates will not lead to similar magnitudes of the wealth effect. Credit remains tight for many households and small business, which should also limit private sector activity. All of these factors combined will probably not be enough to bring about a new recession but will lead to the lowest annual growth rate during this upswing.
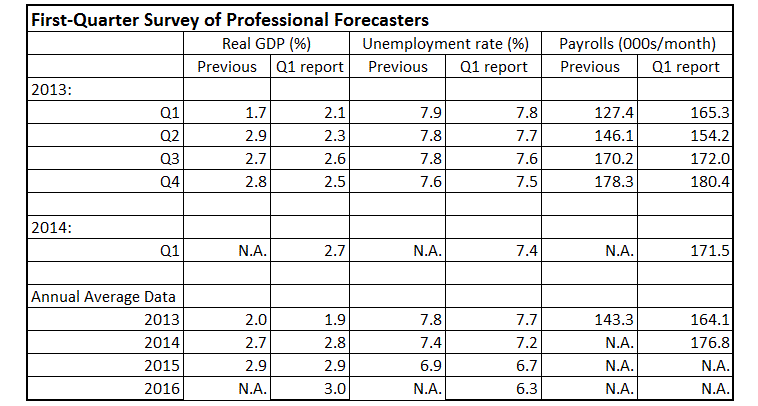

7) U.S. Unemployment rises above 8% - Currently sitting at 7.9%, the unemployment rate is forecast to decline during 2013. Due to weaker GDP growth, corporate revenues will barely rise again this year. As companies face increasing pressure to maintain profit margins at record levels, a new wave of layoffs may occur. Separately, continuing economic growth will encourage previously discouraged workers to re-enter the job market. Both of these factors will lead to slightly higher measured unemployment.

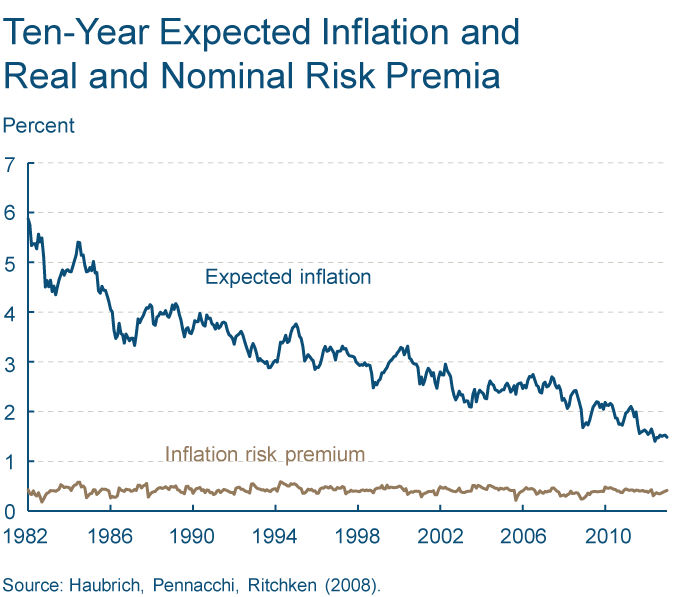
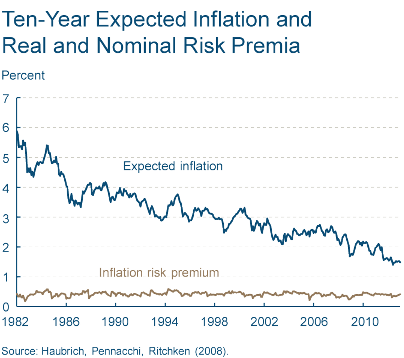
8) Federal Reserve forecasts shift first rate hike to 2016 - After extending their forecast for the first rate hike to 2015, the Federal Reserve changed its tactics to a more rule-based monetary policy. The Fed has, in effect, promised to keep rates low until we've hit either 6.5 percent unemployment or 2.5 percent inflation. Based on the above outlook for unemployment and a continuing decline in inflation expectations (chart below), FOMC members will revise their own forecasts and push back expectations for the first rate hike.

9) U.S. Corporate Earnings (ex-Federal Reserve) finish year below 2012 peak - Meager revenue growth was not enough to prevent U.S. Corporate Profits after tax from reaching record highs in the fourth quarter of 2012 on the back of record profit margins. US Corporate Profits After Tax Chart

As global growth slows in 2013, revenues will come under further pressure. At this point the ability of firms to continue cutting costs without sacrificing output seems limited, which means margins may begin to compress. As margins revert to previous norms, earnings will register a yearly decline.

10) Bonds outperform stocks - During the first seven weeks of this year the stock market has been on fire, even though earnings estimates continue to fall.
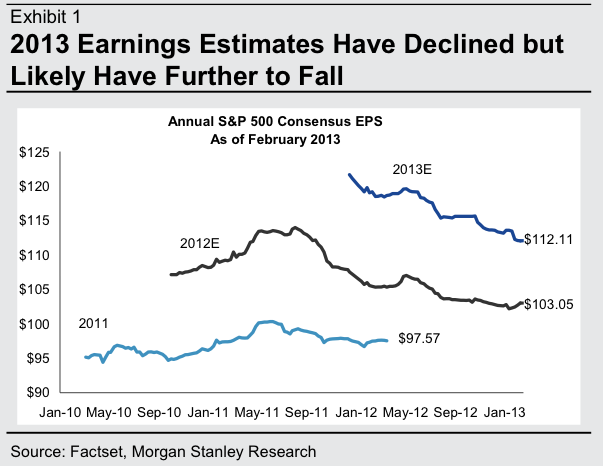

Multiple expansion is currently being driven by the Federal Reserve’s actions despite their ineffectiveness at generating actual NGDP growth. When investors eventually turn their attention to continuing troubles in Europe, ongoing deflation in Japan, and/or weakening growth in China, U.S. earnings may once again enter the picture. Recognition that S&P 500 earnings growth has slowed substantially may cause the market to give up much of this year’s gain. These concerns combined with declining inflation expectations will result in many investors returning to the safety of U.S. Treasuries. The subsequent rise in prices (decline in rates) will generate another year of positive returns for the Treasury market.


Will my predictions prove too pessimistic once again? Only time will tell...

Wednesday, February 13, 2013

The Fed's Massive Accumulation of Treasuries Won't be Unwound

The Federal Reserve Will Need A 'Fairy Tale Ending' To Unwind Its Balance Sheet by Peter Tchir @ Money Game

I don’t see how the Fed announces anything that talks about taking down the balance sheet. Not now, and possibly not ever. The moment people get concerned, the market will start pricing in the unwind, no one will want to buy the long end of the curve and it will play havoc with rates.
Who in their right mind would buy 10 year treasuries when you know that the equivalent of multiple years of supply is being sold by the Fed along with the ones the Treasury department will need to sell. It isn’t like the Treasury department will be able to stop issuing bonds. They have to deal with rolls and frankly with ongoing deficits.
As a hedge fund, are you really going to “fight the fed” and buy 10 year bonds once you think they need to sell them? I don’t think so. More importantly, who will make a nice 10 year mortgage when the 10 year treasury is selling off?
That is the problem. The Fed has built up such a large portfolio, that the only likely way to exit it is through letting it mature. That at least takes the $2 trillion seller out of the market (remember, they are still in buying mode).
Due to the potential damage a sell off occurs, both in the cost of funds for the treasury, but more importantly in the knock on effect it has on other yield products, I would expect the Fed to defend any big move aggressively. Not only do they have the money to do it, but the float is small enough it may take far less than people think to defend the market.
Woj’s Thoughts - Six months ago I argued that an "Interest-On-Reserves Regime" Will Rule Monetary Policy For The Foreseeable Future because:
departing from this new regime will ensure that any future rate hikes be preempted by a reversal of the balance sheet expansion (or excess sale of Treasuries). Balance sheet contraction, through open market operations, could very well depress asset values and raise long-term interest rates. If this occurs, the Fed would be effectively causing a new crisis just as the economy is becoming increasingly stable.
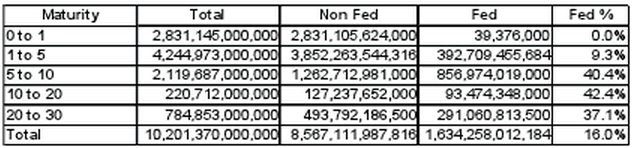
Tchir’s post breaks down the Federal Reserve’s current Treasury holdings, which amount to approximately 40 percent of outstanding supply in the 5 to 30 year maturity range. With the Federal Reserve now purchasing $45 billion of Treasuries per month, those percentages are set to grow rapidly in the coming year(s). Given the potential fallout from even signaling an end to current rounds of QE, I fail to see why future FOMC members would take the risk of actively reducing the monetary base when other options exists. This outlook for monetary policy is precisely why it’s so important to further understanding of the Permanent Floor.

Thursday, January 17, 2013

2012 Predictions: The Results

Last year I took a chance and threw my own projections into the ring. Similar to Byron Wien and Edward Harrison, I mostly selected events that were widely seen as having a low probability (less than 33%) but which I believed held a greater than 50% chance of occurring. Let’s see how I did...

1) Greece leaves the Euro - As the year progresses the Greek economy continues to contract and unemployment continues to rise, surpassing 50% for youth. This combination of factors offsets attempts to reduce the budget deficit as the country repeatedly misses EU and IMF required targets. Despite potential for further bailouts, the Greek people finally decide the consequences of tied promises outweigh the benefits of remaining in the Euro. Greece defaults on all debts, returning to a heavily depressed drachma.

Result - Wrong (0-1). During 2012, Greece was successful in reducing its budget deficit by 30 percent and staying in the Eurozone. This success was in large part due to further defaults on public debt and another bailout. Unfortunately for the Greek people. the price of these efforts remains extraordinarily high. The economy may have contracted as much as 6.5 percent in 2012, the fifth year of recession, according to forecasts in the 2013 budget. Meanwhile both the general and youth unemployment rates continue to soar, reaching ~27 percent and ~58 percent, respectively. At this point Greece is clearly in the midst of a Depression and showing no signs of recovering anytime soon. Greek tolerance of increasing unemployment and decreasing prosperity remains a surprise, although radical political parties have been gaining support. For now Greece remains in the Eurozone, but a future exit remains likely.

2) Italy and Spain lose access to credit markets - A Greek default raises concerns about the potential for creditors to face actual losses on EU sovereign debt. The ECB’s measured efforts are not strong enough to overcome fear and concern about future growth in Italy and Spain. Deep recessions take hold in both countries, pushing deficits higher.

Result - Wrong (0-2). A Greek default and concerns about the European economy weighed heavily on EU sovereign debt during the first half of the year. By the summer, ten-year bond yields in Spain and Italy were at 7.75 percent and 6.75 percent, respectively, and rising. With the countries at risk of losing access to credit markets, ECB President Mario Draghi came forth with a plan to cap sovereign interest rates using open-ended outright monetary transactions (OMT). Draghi’s threat was enough to generate a 180 degree turn in EU sovereign debt markets, but nowhere near enough to turn around the economies. Italy and Spain both returned to recession this past year, pushing fiscal deficits and unemployment higher. While Italy’s unemployment rate remains closely tied to the EU-wide level of ~11 percent, Spain’s general and youth unemployment rates have quickly caught up to Greece’s levels. Eventually Draghi’s Liquidity Bluff Will Be Called, potentially sooner rather than later as a strengthening euro may reignite the EU crisis.

3) The Eurozone enters recession - Practically the entire Eurozone falls into recession, including the likes of France and Germany. A deteriorating economic outlook causes deficit estimates to be raised across the board, facilitating credit rating downgrades. Agreements for greater austerity fail to stem the tide and other attempts to kick the can down the road are pursued.

Result - Correct (1-2). The euro zone economy contracted 0.2 percent in the second quarter and 0.1 percent in the third, meeting the technical definition of a recession. The fourth quarter drop is looking even worse following recent news that Germany  saw output shrink 0.5 per cent between October and December. Although Germany managed to run a slight fiscal surplus, at the expense of growth, Spain’s budget deficit probably exceeded 9 percent for a fourth year in 2012. The first half of the year did witness credit downgrades and austerity agreements, but Draghi’s big kick at the end of summer pushed any further actions into future years.

4) China’s GDP growth falls below 7% - As exports to Europe contract, the busting of China’s housing bubble continues unabated. Expectations for massive monetary easing in Europe and the US, along with fear of flare ups in the Middle East sets a floor under energy and food commodity prices. Monetary easing and fiscal stimulus in China are applied too slowly to prevent growth from slowing below the supposedly necessary 8%. (Note: This will be not be considered a hard-landing, which I deem growth below 5%. That may come in 2013, but for 2012 most economists/analysts will be able to maintain expectations of a soft-landing.)

Result - Wrong (1-3). During the third quarter China’s growth rate slowed to a three-year low of 7.4 percent, but the year-end tally will probably be around 7.7 percent. As growth slowed and housing prices fell early in the year, the government took action to allow a smoother transition between governments. Fiscal stimulus has pushed growth and inflation higher in the last few months, but at the expense of rebalancing the economy toward consumers for future sustainability.

5) Oil prices will spike above $120, finish year below $90 - (Using WTI crude prices, currently ~$102) At some point during the year Iran attempts to block the Strait of Hormuz. Further attempts to overthrow governments in the Middle East, possibly some that only recently gained power, hit the headlines again. Combined with global monetary easing, oil prices will move higher and gasoline will once again hit $4 per gallon in the US. These higher prices will exaggerate the reduction in global demand for other goods and push growth lower. As fears of a global recession take over, oil prices will fall, finishing the year down more than 10%.

Result - Wrong, but close (1-4). Fears about Iran and the Middle East never really materialized this year but that did not prevent a wild ride in oil prices. After rising to over $113 in April, WTI crude prices dropped all the way down to $80 in August (daily price history). A rally in the last week of the year brought the closing price slightly back above $90. Brent crude prices diverged significantly from WTI in 2012, keeping gas prices at the pump high throughout the summer. Gas prices peaked at $3.94, not quite $4, but nevertheless reached a record-high average of $3.62 per gallon.

6) US enters recession in 2nd half - Despite higher 4th quarter GDP in 2011, the lower savings rate and energy prices are unlikely to add much growth in 2012. With Europe contracting and China slowing down more than expected, US exports will take a hit. Extensions of the payroll tax cut and unemployment benefits will help ensure the federal deficit holds above 8%. Housing prices will continue to fall (based on Case-Shiller) causing the savings rate to once again reach 5%. By the end of 2012, the US will be in a recession (although NBER may not confirm this until 2013).

Result - Wrong (1-5). Despite Europe contracting, China slowing down and the federal deficit dropping to 7% (still over $1 trillion), US GDP growth remained positive throughout 2012. After falling to 1.3 percent in the second quarter, annualized GDP growth jumped to 3.1 percent in the third quarter. Although current estimates for fourth quarter GDP are below 1 percent, the US is most likely not in a recession at this time. Partially behind the positive growth was the impact of housing prices rising over 5 percent and the savings rate remaining below 4 percent.   

7) Federal Reserve extends forecasts for ~0% rates until 2015 - As growth in the US weakens once again and the global economy slows, expected inflation over the next ten years (based on Cleveland Fed estimates) will fall towards 1%. With unemployment holding steady around 9%, the Fed will move it’s forecasts for the first interest rate hike out to 2015. (Some form of QE3 is also likely, but aside from promoting short-term speculation, the effects on growth are likely to be muted.)

Result - Correct (2-5). Expected inflation over the next ten years fell consistently during the course of the year to approximately 1.5 percent (chart below). Although unemployment improved materially, dropping below 8 percent, the Federal Reserve still felt the urge to step up monetary stimulus. On September 13th, 2012, the FOMC extended its projections for maintaining “exceptionally low levels for the federal funds rate...at least through mid-2015” while enacting a plan to purchase “additional agency mortgage-backed securities at a pace of $40 billion per month” indefinitely. Since QEternity was insufficient to boost growth, the Fed also enacted QE4 to raise the rate of balance sheet expansion.


8) President Obama will win re-election - Generally a weakening economy has been poor for incumbents but this time will be seen as abnormal circumstances. The troubles in Europe and high unemployment will actually spark desire for a more interventionist government. Given the choice between Obama and Romney, the President will win re-election by a slim margin (2% or less).

Result - Correct (3-5). President Obama crushed Romney in the 2012 election based on the electoral college, however the popular vote was decided by less than 3 percent.

9) The US dollar rises over 5% - (Based on dollar index) In spite of QE efforts and another sizable deficit, the US dollar retains its safe haven status. As fears of European defaults spread and China’s slowing growth impacts commodity prices, the dollar will continue to trend higher.

Result - Wrong (3-6). As fears spread about European default and a slowdown in China, the dollar rose several percent into the summer months. When those fears were assuaged by politicians, not economic data, the euro began a strong rally. By the end of the year, the dollar had essentially finished flat.

10) Bonds outperform stocks - The consensus once again favors stocks, although US Treasuries have now outperformed stocks over the past 1, 10 and 30 year horizons. With global growth slowing, inflation expectations will fall. Before this bull market in bonds ends, 10- and 30-year Treasuries may reach 1% and 2%, respectively.

Result - Wrong (3-7). Slowing global growth, falling inflation expectations and stagnating corporate earnings were not enough to deter stocks from a very strong performance in 2012. The Bernanke put morphed into a proactive Fed determined to push asset prices higher and succeeding to the tune of over 15 percent. While stocks were riding towards new highs, the bull market in bonds also remained intact. The 10- and 30-year Treasuries hit their respective lows of 1.43 and 2.46 during the summer before heading higher into year end. Ultimately 10- and 30-year Treasuries last year posted returns of only 3 percent and 2.5 percent, respectively.   

That’s the end of it. 3-7 is certainly a bit of a disappointment, especially given the direction of events through the first half of the year. That being said, the logic behind each prediction was sound and far more on target than the end result suggests. My main takeaway is that politicians are far more determined to maintain the status quo than I had expected. The underlying economic (and social) problems have once again been kicked down the road for future governments to handle. As long as that pattern holds, current optimism and modest growth can persist for another couple years.

My hope is to have Predictions for 2013 out by the end of next week. Stay tuned.  

Sunday, August 19, 2012

Bubbling Up...8/19/12

1) Chart of the Day: Public deficits and private savings in the euro zone by Edward Harrison @ Credit Writedowns
Budget deficits are what results ex-post from an accounting identity between the sectoral balances and should not be a primary goal of public policy. What we want to do is target the cause of the deficits, insufficient demand which I believe is the result of the overhang of debt after a period of excess private sector credit growth. What you want to do is eliminate that debt overhang by reducing the debt or increasing private sector incomes to support the debt. That’s getting at root causes.

2) How the Economic Machine Works by Ray Dalio @ Bridgewater (h/t Humble Student of the Markets)

[I]f you understand the game of Monopoly®, you can pretty well understand credit and economic cycles. Early in the game of Monopoly®, people have a lot of cash and few hotels, and it pays to convert cash into hotels. Those who have more hotels make more money. Seeing this, people tend to convert as much cash as possible into property in order to profit from making other players give them cash. So as the game progresses, more hotels are acquired, which creates more need for cash (to pay the bills of landing on someone else’s property with lots of hotels on it) at the same time as many folks have run down their cash to buy hotels. When they are caught needing cash, they are forced to sell their hotels at discounted prices. So early in the game, “property is king” and later in the game, “cash is king.” Those who are best at playing the game understand how to hold the right mix of property and cash, as this right mix changes.
Now, let’s imagine how this Monopoly® game would work if we changed the role of the bank so that it could make loans and take deposits. Players would then be able to borrow money to buy hotels and, rather than holding their cash idly, they would deposit it at the bank to earn interest, which would provide the bank with more money to lend. Let’s also imagine that players in this game could buy and sell properties from each other giving each other credit (i.e., promises to give money and at a later date). If Monopoly® were played this way, it would provide an almost perfect model for the way our economy operates. There would be more spending on hotels (that would be financed with promises to deliver money at a later date). The amount owed would quickly grow to multiples of the amount of money in existence, hotel prices would be higher, and the cash shortage for the debtors who hold hotels would become greater down the road. So, the cycles would become more pronounced. The bank and those who saved by depositing their money in it would also get into trouble when the inability to come up with needed cash caused withdrawals from the bank at the same time as debtors couldn’t come up with cash to pay the bank.
Woj’s Thoughts - Although Dalio’s fund may be struggling this year as markets increasingly deviate from economic growth, his insights regarding economic cycles remain a great source of knowledge. In many advanced economies, property was clearly king until the shortfall in cash among households became so pronounced that a debt deflation ensued. The productive portion of the private sector (non-financial) continues to hold too much property and debt relative to cash (savings and income). Rather than encouraging and aiding a “smooth” shift towards cash, public policy remains supportive of reverting back towards property and debt. As long as this mix remains highly unbalanced, economies will prove fragile and prone to crises. (Fun tidbit about me...as a child I loved playing the game of Monopoly. This may have been an early sign that I was destined for a future in economics and finance.)

3) How Long Can Japanese Bond Prices Defy Gravity? by Cullen Roche @ Pragmatic Capitalism

As you likely know, Japan has been suffering a horrid deflation for 20 years as a result of a multitude of factors.  So we’ve witnessed an endless stream of JGB bond traders diving out of windows as they short JGB’s and lose out to ever increasing prices.  One interesting conclusion in the Hoshi/Ito paper is their view on Japan’s ”unrealistically optimistic assumption that Japan’s GDP will grow at 2% annually for the next 40 years”.   If growth is to stagnate then where will the inflation come from?  What could scare these bondholders into a massive JGB revolt leading to higher rates (something which, mind you, did not even occur in the USA during the great stagflation of the 1970′s)?   I am lost for a cause here because Japan’s central bank controls interest rates and as the supplier of reserves to the banking system they can always control the entire yield curve (yes, if they wanted to pin the 30 year bond at a specific rate they would just have to name it and challenge the bond traders to compete with their endless reserve position – the bond traders would lose quickly).
So the question remains – how long can Japanese bond prices defy gravity?  Well, the short answer is – as long as the Japanese central bank is willing to keep rates low.  The more important question is when will Japan experience an environment which forces their central bank to alter the current structure of the yield curve?  Will a stagflation occur similar to the 70s in the USA?  Will a hyperinflation occur for whatever reason?  Will growth rebound?   Or what if Hoshi and Ito’s pessimistic GDP projections are correct?  Then we’re likely to continue seeing JGB traders jumping out of windows following unsuccessful attempts to fight the Bank of Japan.
Woj’s Thoughts - So yes, the Fed can (and to a degree currently does) control long-term interest rates. These questions are equally important for investors currently betting against US Treasuries. When will economic factors cause the Fed to raise interest rates in the foreseeable future? Private sector deleveraging is likely to persist for a few more years and government deficits are decreasing. This suggests a still lengthy period of low growth and inflation, which is consistent with the Fed maintaining short-term rates near zero. The recent sell-off in Treasuries is approaching a level at which the long-side again becomes enticing.  

Monday, August 13, 2012

Modern Money Regimes Redefine Fiscal Sustainability

Mitt Romney’s selection of Paul Ryan as the Republican Vice Presidential candidate ensures that a major focus of the upcoming election will be the federal budget. Many voters appear concerned that continued deficits and an increasing debt-to-GDP ratio will lead to some combination of higher interest rates, slower growth, (hyper) inflation and/or default. In a debate that was already destined to center around this mainstream view of fiscal sustainability, the selection of Ryan will only further cement incorrect theories within public knowledge.

Over the past couple years I have attempted to help further an opposing view of the federal budget, one based on theories of modern money.* Recently I stumbled upon a 2006 paper by Scott Fullwiler, titled Interest Rates and Fiscal Sustainability, which offers a surprisingly complete explanation of a modern money regime. Presenting the major departures from mainstream views, Fullwiler concludes:

“in a modern money regime such as the U. S., deficits do not crowd out but rather create net financial assets for the non-government sector, the operational purpose of bond sales is interest-rate support, and the Fed’s interest rate target anchors other short-term rates given that tax liabilities must be paid in reserve balances. As a result of these regime characteristics, the interest rate on the national debt is a monetary phenomenon that primarily reflects the current (and expected, if long-term, fixed-rate time deposits are issued) interest-rate “anchor” set by the Fed, not the size of the current or expected future levels of the debt or deficits as assumed in the loanable fund market paradigm. This monetary nature of interest on the national debt is indisputable when one considers that the federal government never needs to issue its debt as time deposits and could simply create (assuming a positive interest rate target) interest-bearing reserve balances that earn interest at the Fed’s target interest rate, as in the proposals discussed earlier. Self-imposed constraints, including legal restrictions on operating procedures or lack of political will, might keep a simplified procedure such as this from being implemented, but they do not change the monetary nature of rates paid on the national debt; the choice to issue short-term or long-term securities (i.e., non-government sector time deposits at the Fed) is simply a more complicated version of this more general or (in the case of a zero interest rate target) “natural” case. (p.26)”
For readers interested in fiscal and/or monetary policy, Fullwiler’s paper is a fantastic resource. Over the coming days it is my intention to offer a more detailed examination of the various principles outlined above with further excerpts from the paper and real-world applications. Even if the basic principles of a modern monetary system supplants current mainstream theories, clear cut policy choices will remain out of reach. The policy conversations, however, will improve dramatically and the likelihood of better outcomes will increase significantly.

* I mention theories of modern money rather than Modern Monetary Theory (MMT) to include support for Monetary Realism, Post-Keynesians, Circuitistes, Horizontalists and others that accept the basic principles laid out by Fullwiler.

Friday, August 3, 2012

Bubbling Up...

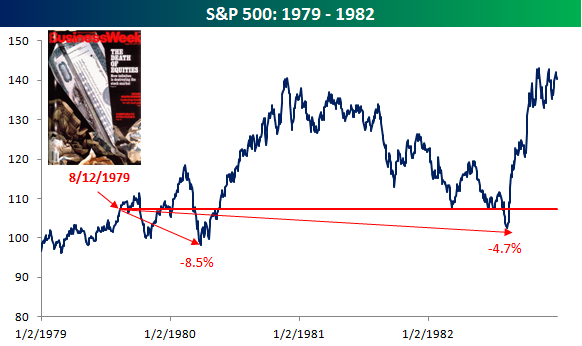
1) How Good An Indicator Was "The Death of Equities" Cover
Just how good of a buying indicator was the BusinessWeek cover from 1979, though?  If you ask most investors about that cover story, they seem to remember that the market almost immediateley took off after the issue was published.  The reality, however, is that nearly eight months after the cover story was published, the S&P 500 was down 8.5%.  While the market did rally from that level, three years after the infamous BusinessWeek cover, the S&P 500 was still down nearly 5%.  It wasn't until 8/12/82 that the S&P 500 really took off and the bull market began in earnest.  Granted, time horizons have gotten a lot shorter in the last thirty years, but three years is an eternity in this market.


Woj’s Thoughts - Our memories can deceive us by filling in stories with logical steps. Cover stories often do mark extremes in sentiment, yet those extremes may persist for quite some time. As a signal for contrarian investors, recognizing this reality is critical.

2) Why I don’t believe housing has put in a secular bottom by Edward Harrison

For the bottom to be in you have to believe two things from a macro perspective. First, you have to believe that the overshoot phase to the downside has been arrested. Most bubbles end with a significant overshoot that makes it a no-brainer to tip a toe in the market. I think we are approaching those levels in markets like Phoenix. But we never really got down to reasonable levels in places like Washington or New York. Second, you have to believe any US recession is both remote in time and mild in duration/severity. I question this. I think any US recession will re-start the house price decline dynamic because consumers are still overindebted, interest rates are at zero percent, and mortgage rates are as low as they can get. My point is that from a cyclical perspective 2012 is as good as its going to get. Calling a bottom at the top of a cyclical bull market in asset prices and the economy is folly. Wait until the bottom of the cycle to make those calls.
Woj’s Thoughts - Early this year I made the claim, Don't Rush to Buy a Home! At the end of May I was Still Not Buying A Housing Recovery. Edward lays out many/most of the reasons for my continued lack of optimism on housing prices over the next couple years.
 
3) The Evolution of Treasury and Muni Bond Yields by Cullen Roche
I’ve discussed this in detail over the years and why the analysts crying for mass US state insolvencies were likely to be wrong, but now we have some interesting new analysis via VOX.  What’s depicted below is the 10 year US Treasury versus the 10 year muni bond index.  As you can see, the yields have an extremely high correlation – muni bonds practically ARE treasury bonds.  So why are yields surging in Italy, Spain, Greece and Portugal, but they’re remaining so tame in the muni market?  Simple – the US government, which can always procure funds via taxes and bond sales therefore making solvency a non-issue, provides substantial federal aid to the states every year.  While this doesn’t eliminate the solvency issue at the state level it certainly helps reduce it substantially.  Europe has no such mechanism in place so what you basically have is a bunch of US states in an environment where they’re left to fend for themselves.  They can’t print their own currency, they can’t devalue their own currency and they can certainly run out of Euros.  The result is bond investors who are terrified about default and end up selling bonds which only exacerbates the budgeting process.*
4) Microfoundations and the capital debates by Matias Vernengo
In that sense, heterodox (classical-Keynesian, by which I mean Sraffa’s prices cum Keynes/Kalecki’s effective demand) does have a coherent determination of long run prices, based on rational behavior, as the foundation of the macroeconomic theory. Markets do not produce optimal outcomes and unemployment of productive resources is the normal, long run, position of the economy. In fact, the capital debates not only say that classical political economy (the surplus approach) provides sound microfoundations, but also that it is NOT possible to do so within the neoclassical/marginalist paradigm.
Woj’s Thoughts - Previously I’ve argued against microfoundations in macroeconomics, but Matias places an interesting spin on the discussion. Quite possibly the issue is not the use of microfoundations but rather the poor choice of microfoundations.

5) Another Summer of Discontent: The Four Factors that Explain Why What We’re Doing Isn’t Working by Daniel Alpert

We must move from stabilize and reflate, to stabilize and recalibrate:
  • It is time for creditors throughout the developed world to finally take the write downs that have long been coming their way in connection with the trillions of dollars of truly un-payable household and sovereign debts that resulted from the credit bubble of the 2000s.  Yes, this will pressure lenders and, yes, they will need to be recapitalized to the detriment of their existing stakeholders.  But there is presently no shortage of capital seeking reasonable risk-adjusted returns, and I have every confidence that it will flow eagerly into the financial sector—if only the balance sheets of our institutions were honestly reckoned by having the currently unrecoverable carrying value of assets written down to that which can be recovered today from borrowers and/or underlying collateral.

  • As I have been saying and writing about for years, we must accept the reality of what the credit markets are telling the planet’s most creditworthy governments, particularly that of the U.S.  The message is “please, here, take our money…take it cheaply and keep it safe…we have no fear of lost purchasing power, the trend is not inflationary…now take it (and use it to fix your  economy).” And that is what we must do. We must take as much 30-year money at these depression level interest rates as we need to re-employ our underemployed workers directly, on public infrastructure projects that return benefits to the economy more than sufficient to repay the sums borrowed when the time comes.  The private sector will not hire until it sees a recovery in demand—so the only agent for re-employment of workers and regeneration of demand may, for an extended time until the imbalances at least decline somewhat, be our governments.  It is long past time to pack away austerity agendas.

  • And yes, we must address and manage the process of nominal price, wage and asset value declines. The advanced economies are experiencing the effects of a supply glut, a debt overhang, massive technology-induced productivity (soon to transfer to the emerging economies, worsening the glut), and aging populations. These are all disinflationary factors. And the aggregate effect of their contemporaneous existence is deflationary—full stop. Yet in relying on monetary intervention alone we are fighting the battle to control the pace of deflation (forget about reflation) with one hand tied behind our back.n  Instead of targeting growth in nominal GDP, which I am proclaiming here to be a futile endeavor, we must target renewed global competitiveness and, at the very least, growth in real GDP. That means both allowing our price and wage structures to align themselves with global supply and demand and, more importantly, feeding and nurturing investment in those areas of the private sector that can employ large numbers of people at market clearing wage rates. Especially in those sectors that are more readily protected by geography from global competition.

Friday, July 27, 2012

The Fed Controls Long-Term Interest Rates

Casey Mulligan recently offended a significant portion of the economics blogosphere by stating that:
New research confirms that the Federal Reserve’s monetary policy has little effect on a number of financial markets, let alone the wider economy. Politicians, and a few economists, have been imploring the Federal Reserve to help the economy grow before November. But the effects of monetary policy on the wider economy are small.
Although I have repeatedly attempted to show that, under current conditions, monetary policy would be largely ineffective at stimulating the broader economy, this should not be taken as a dismissal of the general potential for monetary policy. Cullen Roche chimes in on the subject with a conclusion that sums up my views:
monetary policy has been very weak in the current environment for several reasons.  The primary reason is due to a lack of demand for debt.  Consumers are saddled with excessive debt so demand for “inside money” has been abnormally weak in recent years.  This is perfectly normal following a credit driven bubble.  And since monetary policy primarily works through altering the cost of “inside money” it’s not surprising that the actions of the Fed have appeared rather ineffective in recent years.  But this unusual environment should not be taken to mean that the Fed has zero options or that monetary policy is never effective.    To do so would be a vast misunderstanding of the basics of banking and the way our monetary system works.  Monetary policy might be a blunt instrument at times, but let’s not make extreme comments that sound ideological or take the uniqueness of today’s environment to make sweeping generalizations.
Beyond this main issue concerning the effectiveness of monetary policy, Mulligan’s post raised the question of whether the Federal Reserve controls long-term interest rates. Since the Federal Reserve could purchase all outstanding Treasuries at a given price/yield, I think it’s fair to say the potential power for strict control exists. A more basic question, however, is whether past and current policy displays control over long-term Treasury rates. I’ve argued affirmatively, drawing on comments from Edward Harrison, Gary Becker and others, that long-term Treasury rates are primarily a function of expected short-term rates over a given period. JW Mason, whose work I highly regard, disputes this claim:
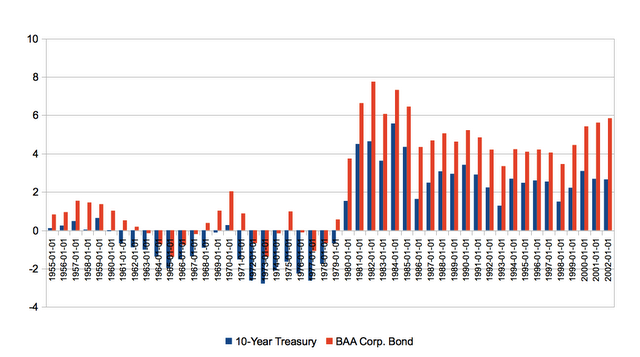
it's not at all obvious that long rates follow expected short rates either. Here's another figure. This one shows the spreads between the 10-Year Treasury and the Baa corporate bond rates, respectively, and the (geometric) average Fed Funds rate over the following 10 years.
If DeLong were right that "the long government bond rate is made up of the sum of (a) an average of present and future short-term rates and (b) term and risk premia" then the blue bars should be roughly constant at zero, or slightly above it. [2] Not what we see at all. It certainly looks as though the markets have been systematically overestimating the future level of the Federal Funds rate for decades now. But hey, who are you going to believe, the efficient markets theory or your lying eyes?
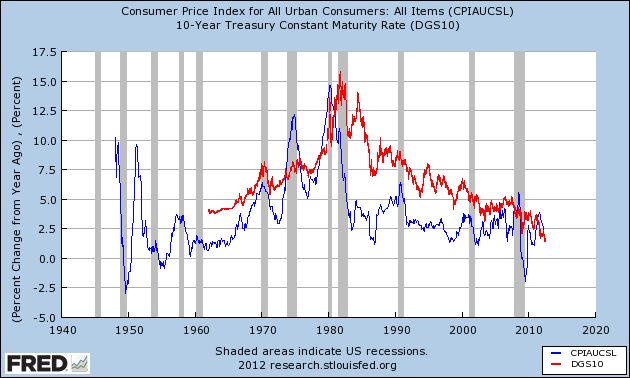
From my perspective, this preliminary conclusion from Mason confuses expected average rates with actual outcomes. Although I can’t speak for DeLong (or others), the notion that markets might/have systematically overestimated and underestimated future Fed Funds rates does not undermine the theory. As the following chart shows, inflation and 10-year Treasury rates were primarily rising from the early 1960’s until the early 1980’s. Based on economic theory at the time (e.g. Phillips curve), it was not unreasonable to expect that inflation would subside with increasing unemployment and the Federal Reserve would lower rates in response. The unexpected persistence of inflation likely caused many investors to consistently underestimate future Fed Funds rates during this period.

By the time Paul Volcker took over as Chairman of the Federal Reserve, many (most) investors had probably come to expect persistent inflation. When inflation crashed in the early 1980’s, it would have been equally reasonable to expect a return to high inflation and Fed Funds rates. The actual outcome has been largely subdued inflation, now going on 30 years. To understand how unexpected this outcome was, one only has to consider that returns on long-term Treasuries has exceeded returns on stocks during this 30-year period (a previously unthinkable feat missed by nearly all investors).

Mason continues his post with the counter claim that:
What profit-maximizing bond traders do, is set long rates equal to the expected future value of long rates.
I went through this in that other post, but let's do it again. Take a long bond -- we'll call it a perpetuity to keep the math simple, but the basic argument applies to any reasonably long bond. Say it has a coupon (annual payment) of $40 per year. If that bond is currently trading at $1000, that implies an interest rate of 4 percent. Meanwhile, suppose the current short rate is 2 percent, and you expect that short rate to be maintained indefinitely. Then the long bond is a good deal -- you'll want to buy it. And as you and people like you buy long bonds, their price will rise. It will keep rising until it reaches $2000, at which point the long interest rate is 2 percent, meaning that the expected return on holding the long bond and rolling over short bonds is identical, so there's no incentive to trade one for the other. This is the arbitrage that is supposed to keep long rates equal to the expected future value of short rates. If bond traders don't behave this way, they are missing out on profitable trades, right?
Not necessarily. Suppose the situation is as described above -- 4 percent long rate, 2 percent short rate which you expect to continue indefinitely. So buying a long bond is a no-brainer, right? But suppose you also believe that the normal or usual long rate is 5 percent, and that it is likely to return to that level soon. Maybe you think other market participants have different expectations of short rates, maybe you think other market participants are irrational, maybe you think... something else, which we'll come back to in a second. For whatever reason, you think that short rates will be 2 percent forever, but that long rates, currently 4 percent, might well rise back to 5 percent. If that happens, the long bond currently trading for $1000 will fall in price to $800. (Remember, the coupon is fixed at $40, and 5% = 40/800.) You definitely don't want to be holding a long bond when that happens. That would be a capital loss of 20 percent. Of course every year that you hold short bonds rather than buying the long bond at its current price of $1000, you're missing out on $20 of interest; but if you think there's even a moderate chance of the long bond falling in value by $200, giving up $20 of interest to avoid that risk might not look like a bad deal.
Once again, I think this example confuses some aspects of bond trading. While Mason considers a bond in perpetuity, let’s instead consider a 10-year Treasury with a 4% yield and 2% Fed Funds rate expected to continue indefinitely. Now assume that this expectation for the Fed Funds rate holds true. Entering year ten, if prices don’t adjust, investors will have the option of purchasing notes with equal maturities (the 10-year Treasury only has a year remaining before maturity) that offer either a 2% or 4% yield. Given the option, investors will purchase the 4% note, pushing the price up and yield down until it reaches approximately 2%. Even if 10-year Treasury rates are still 4% at that time, the previously held bond no longer has a long-term maturity and becomes the equivalent of a short-term note/bill. This is why the expected short term rates, and not long-term rates, matter for controlling long-term Treasury rates.     

Despite our differences in opinion over influencing long-term Treasury rates, Mason and I agree that:
for policy to affect long rates, it must include (or be believed to include) a substantial permanent component, so stabilizing the economy this way will involve a secular drift in interest rates -- upward in an economy facing inflation, downward in one facing unemployment. (As Steve Randy Waldman recently noted, Michal Kalecki pointed this out long ago.)
Currently, unemployment and disinflation are persisting far longer than most economists, politicians and investors expected. These outcomes have led the Federal Reserve to maintain a zero percent Federal Funds rate for three years and predict continuation of that policy for at least a couple more. As investors become increasingly convinced that short-term rates will remain at or near zero indefinitely, long-term Treasury rates have continued the secular drift lower that began in the early 1980’s.

So yes, the Federal Reserve can control long-term Treasury rates and has been doing so by adjusting market perceptions of future Fed Funds rates. Unfortunately, as Mason says:
adjusting expectations in this way is too slow to be practical for countercyclical policy.
Monetary policy, in a future crisis, will once again have its time to shine. For now, fiscal policy must take center stage to reduce household debt burdens and counteract previous measures aimed at inducing a credit bubble.